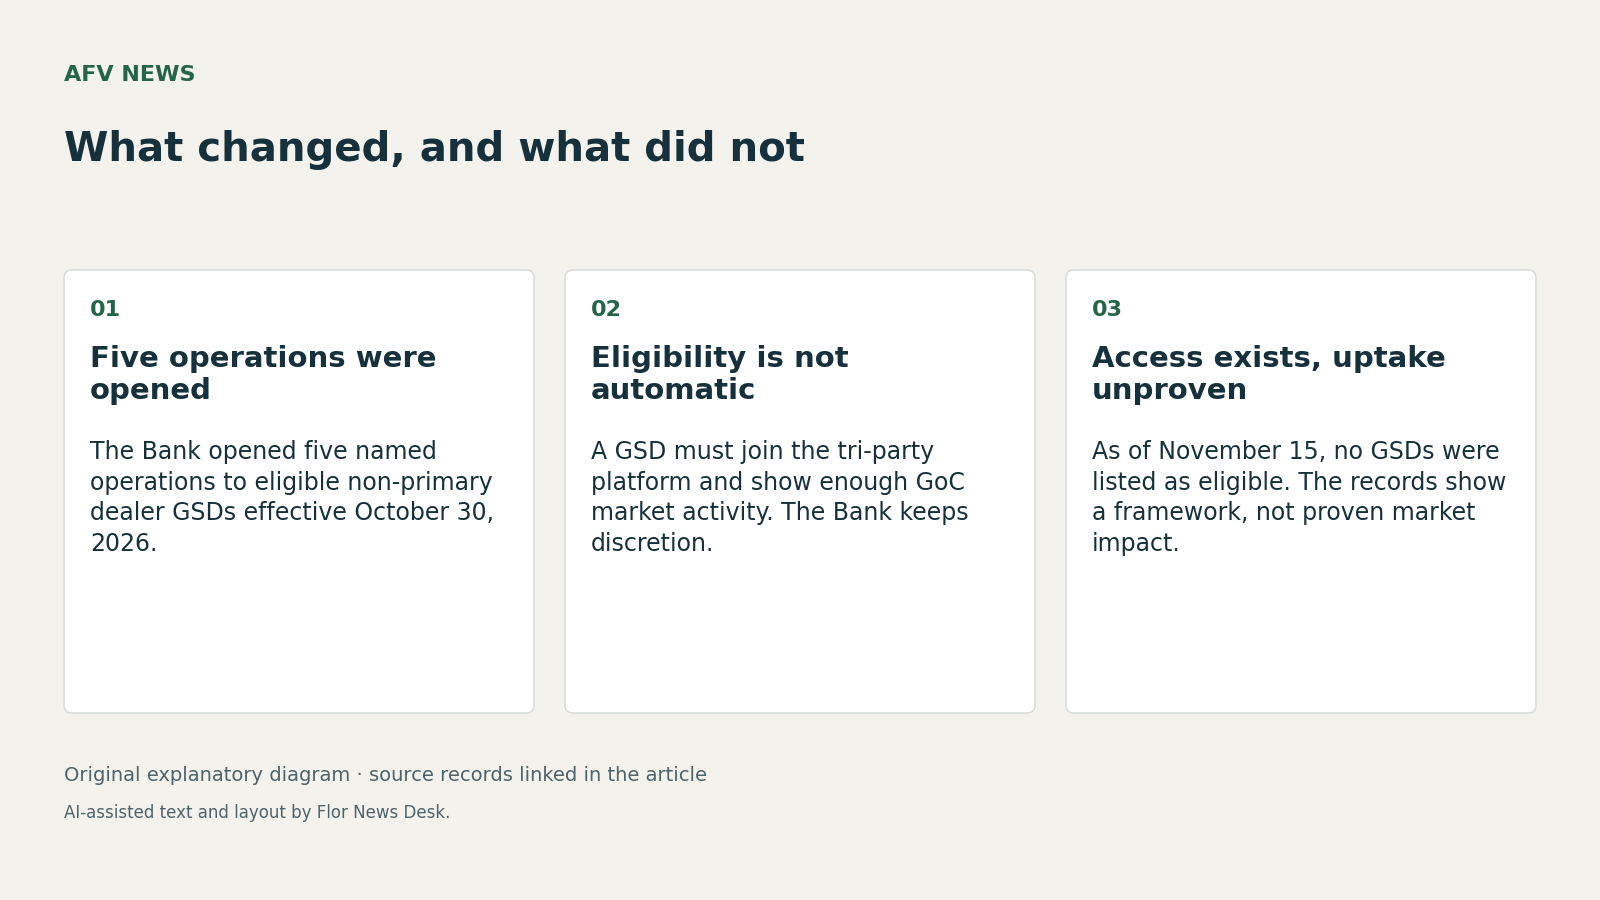
The Bank of Canada made a concrete market-structure change on October 29, 2026: effective October 30, eligible non-primary dealer government securities distributors can seek access to five Bank operations that were previously limited more narrowly. The notice names Overnight Repo, Overnight Reverse Repo, two-week Term Repo, the Overnight Standing Repo Facility and the Securities Lending Program. It also says access is not automatic and will be decided at the Bank’s discretion. Market notice
For Canadian dealers and treasury teams, the main business point is that the policy change is broader than a one-off facility tweak but narrower than an open invitation. The Bank’s eligibility page says a non-primary dealer GSD must belong to the Canadian Collateral Management Service tri-party platform and must demonstrate and maintain sufficient activity across Government of Canada primary, secondary and repo markets. The same page says eligibility is considered on request, can include other Bank-set requirements and remains subject to periodic review. Eligibility guidance
That distinction matters because the records do not show a new class of counterparties actually operating yet. The guidance page states that no government securities distributors were currently eligible as of the November 15, 2026 retrieval captured in the source brief. The Bank’s October 29 notice established the framework and start date, but the available records do not identify any approved firms, any onboarding timetable or any completed participation in those operations. Eligibility guidance Market notice
The practical implication is that October 30 was an implementation date for a process, not proof of immediate market access at scale. A firm interested in the facilities would still need operational readiness through the tri-party platform and enough measurable Government of Canada market activity to satisfy the Bank. Because the Bank did not publish numeric thresholds for that activity in the cited records, outside firms cannot infer that GSD status alone, trading volume alone or simple application timing will be enough. Eligibility guidance
The competitive effect also appears limited, at least on the source record now available. The October 29 notice says eligible non-primary dealer GSDs will have lower participation limits than Primary Dealers under each operation’s terms and conditions. That supports a cautious reading: the Bank is widening the pool of potential users without granting equivalent access. Analysis: if participation caps remain lower and approvals remain discretionary, the first change for the market is more optionality at the margin, not a documented reshaping of dealer hierarchy or funding costs. The records do not quantify those caps or any pricing effect, so stronger claims would go beyond the evidence. Market notice
The Bank’s homepage, as retrieved on November 15, still listed the October 29 market notice, which confirms the notice remained part of the Bank’s current public communications. But that landing page does not add evidence that any firm has qualified or that market liquidity has measurably changed. It is useful mainly as a reminder to separate announcement visibility from operational uptake. Bank homepage listing
For AFV News readers, the immediate takeaway is operational rather than promotional. There is now a published path for some non-primary dealer GSDs to seek Bank access across repo and securities-lending channels, but the public record still shows a controlled gateway: tri-party membership, demonstrated market activity, discretionary approval, periodic review and lower limits than Primary Dealers. Until the Bank publishes approved counterparties or usage data, the change is best understood as a live opening of eligibility criteria, not yet a demonstrated shift in market outcomes. Market notice Eligibility guidance
Read our editorial standards or send a correction to the editorial desk.